$2,500 Cap, 36% Rate: Virginia Title Loan Laws Mapped to Code
Virginia allows motor vehicle title loans, but Chapter 22 of the Code of Virginia keeps them on a short leash: a $2,500 principal cap, a 36 percent simple annual interest limit, and mandatory licensing for every lender, including online ones. If a lender skips the license, the loan is void. Verify any lender and file complaints through the Virginia State Corporation Commission’s Bureau of Financial Institutions, which regulates every title lender operating in the Commonwealth.
TL;DR:
- Lenders must be licensed in Virginia, and loans made without a license are considered void, stripping them of legal collection rights.
- The principal limit is $2,500, with a maximum interest rate of 36 percent per year and monthly maintenance fees capped at the lower of 8 percent of the loan or $15.
- Illegal practices include demanding unapproved fees, requiring add-on products, taking collateral beyond the vehicle, or repossessing before proper notices are given.
- Default procedures require a 10-day written notice, with borrowers retaining the right to redeem the vehicle and limits on deficiency judgments.
- Always verify licensing and review total fees and interest calculations before signing, especially with online lenders operating within Virginia’s legal framework.
Table of Contents
- Who Regulates Virginia Title Loan Laws and Who Needs a License
- What Virginia’s Interest Rate Cap and Fee Limits Actually Allow
- Business Practices Virginia Title Lenders Are Barred From Using
- What Happens if You Default: Repossession, Redemption, and Sale
- How to Verify a License and File a Complaint With the SCC
- Your Pre-Signing Checklist for a Virginia Title Loan
- Why the Statute, Not the Sales Pitch, Should Set Your Expectations
- Considering an Online Option? What Cashtitleexpress Puts in Writing
- Sources
- FAQ
Who Regulates Virginia Title Loan Laws and Who Needs a License
A “motor vehicle title loan” under Virginia law is a loan secured by a lien on your car title that isn’t tied to the purchase of the vehicle itself. That distinction matters: a loan you take out to buy a car from a dealer, financed through the dealer or a bank, isn’t a title loan under this chapter. A loan where you hand over your paid-off car’s title as collateral for cash, unrelated to buying the car, is exactly what Chapter 22 governs.
Every company that makes or brokers these loans to Virginia residents needs a license from the Bureau of Financial Institutions. Under § 6.2-2201, a loan made without that license isn’t just improper. It’s void. That means the lender may have no legal right to collect interest or fees, and in some cases none at all, though the exact remedy depends on the specifics of the case. Banks, credit unions, and savings institutions are exempt because they operate under separate federal and state banking supervision.
The law doesn’t stop at Virginia’s borders. Under § 6.2-2225, Chapter 22 applies to internet lenders making loans to Virginia residents even when that lender has no physical office in the state. This closes an obvious loophole: a company can’t dodge Virginia’s rate caps and licensing rules just by operating a website from another state.
Here’s what that scope means in practice:
- If you live in Virginia and pledge your car title for cash, the lender needs a Virginia license, no matter where the lender’s servers or storefronts are located.
- Purchase-money vehicle financing (auto loans from the dealership or bank) is not covered by this chapter.
- Banks and credit unions making title-secured loans fall outside Chapter 22’s specific licensing regime.
- A loan made by an unlicensed title lender to a Virginia resident is void, which strips away much of the lender’s normal right to collect.
This licensing requirement is also why checking a lender’s status before signing anything isn’t optional. It’s the single fastest way to confirm you’re dealing with a business that Virginia actually recognizes as legitimate.
What Virginia’s Interest Rate Cap and Fee Limits Actually Allow
The dollar figures in Chapter 22 are specific, and they’re worth knowing before you ever sit down with a contract. § 6.2-2215.1 caps the principal on a motor vehicle title loan at $2,500. Loan terms have to run at least six months and no more than 24 months, though the statute allows certain income-based exceptions that can shift those boundaries for specific borrowers.
Interest is capped too. Under § 6.2-2216, a licensee can’t charge more than a simple annual rate of 36 percent. On top of that, lenders can charge a monthly maintenance fee, but it’s capped at whichever is lower: 8 percent of the original loan amount or $15 a month. Aggregate fee limits in § 6.2-2216 and § 6.2-2216.4 also cap total charges relative to the original loan size, generally in the range of 50 to 60 percent depending on the loan’s size and structure.
By the numbers: Virginia caps title loan principal at $2,500, interest at a 36 percent simple annual rate, and monthly maintenance fees at the lesser of 8 percent of the loan or $15, under § 6.2-2216.
A handful of other charges are permitted outside those core numbers, but they’re narrow:
- A reasonable fee for a returned or dishonored payment item.
- A capped late fee for missed payment deadlines, spelled out in the loan agreement.
- No charges beyond what the statute explicitly authorizes; anything else billed as a “fee” that isn’t named in § 6.2-2216 is a red flag.
Disclosure requirements go hand in hand with these caps. Every loan has to be documented in a written contract that spells out the principal, the interest rate, the maintenance fee, the total amount due, and the loan’s maturity date, consistent with the loan-terms rules in § 6.2-2215.1. You’re entitled to a signed copy of that contract before you leave with the cash, not after. Separately, administrative code guidance under 10VAC5-210-30 requires lenders to provide a motor vehicle title lending pamphlet and bars them from giving false or misleading information about loan terms.
The aggregate-fee caps deserve a second look because they catch problems the interest rate alone won’t. A lender can technically stay under 36 percent interest while still stacking enough add-on charges to push your real cost of borrowing far higher, unless the total is checked against the statutory ceiling. Add up every fee on your contract, not just the interest line, and compare that total against the loan’s original principal.
Business Practices Virginia Title Lenders Are Barred From Using
Chapter 22 doesn’t just cap what lenders can charge. It also draws a hard line around how they’re allowed to behave. Under § 6.2-2215, the Code sets out required and prohibited business methods that every licensed title lender in Virginia has to follow, regardless of loan size.
Several practices are flatly off-limits:
- Charging any fee or ancillary product cost not explicitly authorized under § 6.2-2216.
- Requiring you to buy insurance, warranty coverage, or other add-on products as a condition of getting the loan.
- Taking a security interest in anything other than the motor vehicle titled in your name, meaning a lender can’t demand your house keys, a second vehicle, or unrelated property as backup collateral.
- Debiting your bank account or drafting funds without your specific written authorization for that transaction.
- Repossessing your car before the notice period required under § 6.2-2217 has run.
Refinancing and renewal practices get scrutiny too, since rolling a loan over is one of the easiest ways for total costs to spiral. Lenders can’t structure serial renewals in a way that functions as an end run around the interest and fee caps, and taking out multiple simultaneous title loans against the same vehicle isn’t something a compliant lender will let you do, since only one lien can attach to the title at a time in practice.
Collection behavior is regulated as well. A licensee has to follow the notice and timing rules in § 6.2-2215 and § 6.2-2217 before taking your car, and communication practices around collecting a debt carry constraints similar in spirit to federal fair debt collection standards, even though Chapter 22 is a state statute rather than a federal one.
Pro Tip: Read the “Prohibited Practices” language in your contract before you sign, not after a dispute starts. A lender that won’t put its fee schedule in writing, or that pushes you to buy an add-on product, is very likely already outside what Virginia law permits.
What Happens if You Default: Repossession, Redemption, and Sale
Default doesn’t give a Virginia title lender free rein over your finances beyond the car itself, and that limit is one of the most borrower-favorable parts of Chapter 22.
- Notice comes first. The lender must send a written default notice at least 10 days before repossessing your vehicle, and that notice has to spell out what you owe, the deadline to cure the default, and your right to redeem the vehicle.
- You can redeem before sale. Even after repossession, you generally retain the right to get your car back by paying the amount actually due, and the lender has to give you an accounting of that figure rather than an inflated demand.
- Sale proceeds are accounted for. If the vehicle is sold after a valid repossession, proceeds go first to the loan balance and lawful fees; anything left over belongs to you, the borrower.
- Deficiency judgments are the exception, not the rule. Under § 6.2-2217, a lender’s recourse is generally limited to repossessing and selling the car. A personal money judgment against you is allowed only in narrow situations, such as fraud, concealment, or intentional damage to the vehicle.
That last point is worth sitting with. In most other consumer lending, a shortfall after a repossession sale can turn into a debt collector’s target for years. Virginia’s structure pushes that risk back onto the lender in ordinary default cases, which changes the practical math of walking away from a struggling loan.
How to Verify a License and File a Complaint With the SCC
Before you sign anything, confirm the company holding your title is actually licensed. The Bureau of Financial Institutions runs a “Verify a License” lookup tool through the State Corporation Commission, and it takes a few minutes to check a company name against the state’s active license list.
If something’s gone wrong, the Bureau handles consumer complaints directly. You can file online through its complaint form, or call 804-371-9657 for phone assistance if you’d rather talk through the issue first.
Worth knowing: the Bureau of Financial Institutions can investigate licensed lenders, order corrective action, and refer serious violations for further enforcement, but it can’t act as your personal attorney or guarantee a specific outcome in your individual dispute.
When you file, bring documentation:
- A copy of the signed loan contract, front and back.
- Payment records showing what you’ve paid and when.
- Any written communication from the lender, especially default notices or collection letters.
- Screenshots or records of online applications if you dealt with an internet lender.
A complaint with thin documentation is harder for the Bureau to act on quickly. A complaint with a clear paper trail moves faster and gives investigators something concrete to check against the statute.
Your Pre-Signing Checklist for a Virginia Title Loan
Treat every one of these as non-negotiable before you sign:
- Ask for the lender’s license number and confirm it through the Bureau of Financial Institutions before you hand over your title.
- Get the full written contract, and check the interest rate and total fees against the 36 percent cap and the aggregate-fee limits in § 6.2-2216.
- Confirm the lender will properly note its lien on your title with the DMV within the required timeframe, so there’s no confusion later about who holds the security interest.
- If you’re applying online, confirm the offer names Virginia-specific terms rather than generic, one-size-fits-all numbers, since the same-day title loan funding process still has to follow state rate caps.
- Ask directly whether there’s a prepayment penalty. Virginia law doesn’t require lenders to waive one, so this needs to be confirmed in writing, not assumed.
Pro Tip: Screenshot or save a PDF of any online offer the moment you receive it. Terms on a lender’s site can change, and having your own timestamped copy protects you if the final contract doesn’t match what you were shown.
Why the Statute, Not the Sales Pitch, Should Set Your Expectations
Most consumer advice about title loans treats the interest rate as the whole story. It isn’t. Virginia’s aggregate-fee caps and its limited-recourse rule on default matter just as much, and they’re the parts borrowers skip past because the numbers take a minute to calculate.
The conventional wisdom, “avoid title loans entirely,” ignores that Virginia already built real guardrails into the product: a 36 percent rate ceiling, a $2,500 principal cap, and a default framework that generally keeps your other assets off the table. That doesn’t make the loan free or risk-free. It means the risk is more contained than most general lending horror stories suggest, provided the lender is actually licensed and the contract actually matches the statute.
What should come first isn’t shopping for the lowest advertised rate. It’s confirming the license and doing the fee math yourself before you sign. A compliant lender should have no problem with either request. One that resists is telling you something.
— Constantine
Considering an Online Option? What Cashtitleexpress Puts in Writing
If you’d rather handle the whole process from your phone or laptop, online car title loans through Cashtitleexpress work within the same Virginia rate and licensing structure covered above, connecting borrowers with licensed lenders and presenting written, state-specific loan terms before you accept anything.
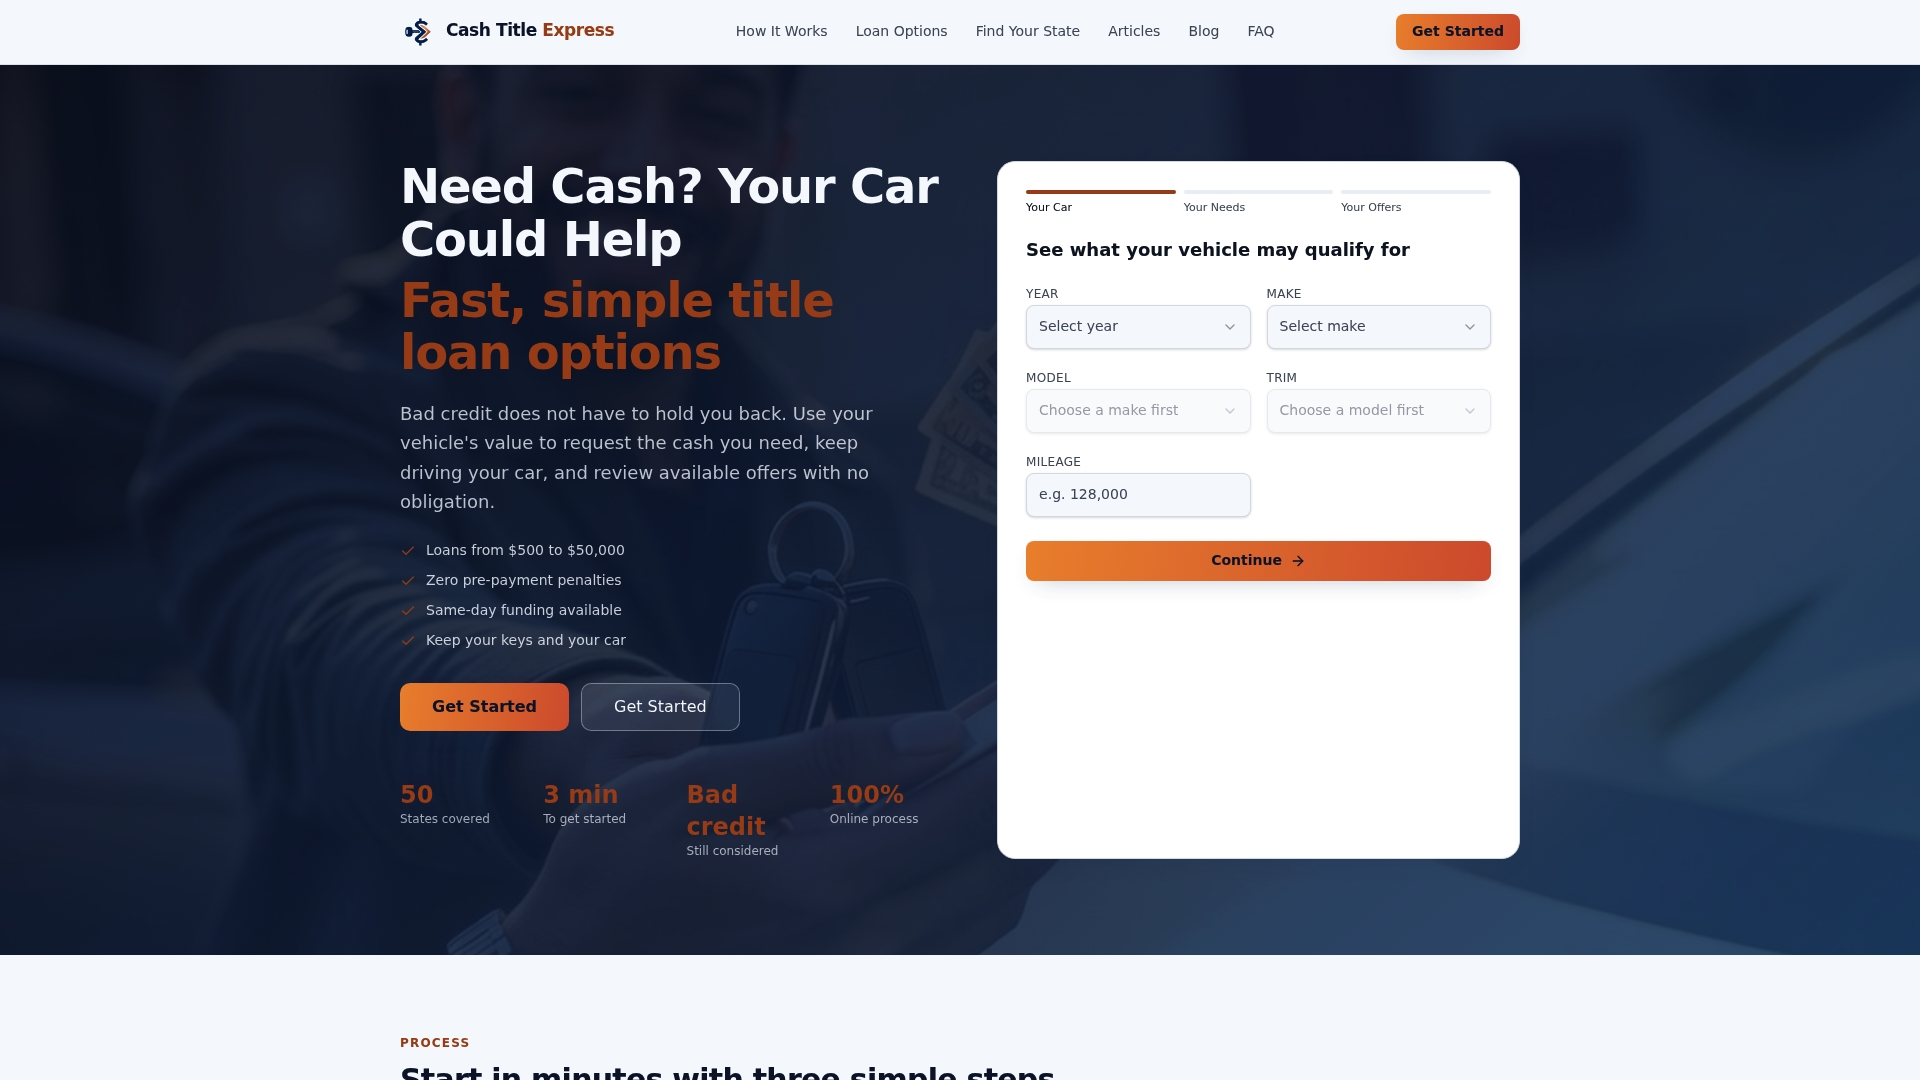
The offer you see spells out the principal, the rate, and the fees, matched to Virginia’s statutory caps, with no obligation to accept it. Loans arranged through an online platform may have no prepayment penalties, and borrowers can keep driving their car during the loan since there’s no vehicle surrender involved. Loan amounts vary depending on your vehicle and what a licensed lender approves for your situation. Before you accept any offer, confirm the lender’s license through the Bureau of Financial Institutions the same way you would with any other title lender. Check your eligibility requirements and start an application to see a written offer with no commitment attached.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What happens if you never pay a title loan back in Virginia?
If you default, the lender must send a written notice at least 10 days before repossessing your car, and you generally keep the right to redeem the vehicle before it’s sold. Under § 6.2-2217, the lender’s recourse is normally limited to repossession and sale, not a personal judgment against your other assets, except in cases involving fraud or intentional damage to the vehicle.
Can I get a title loan in Virginia from an out-of-state lender?
Any lender making title loans to Virginia residents needs a Virginia license, even if that company operates entirely online with no physical office in the state. § 6.2-2225 specifically extends Chapter 22’s licensing and rate rules to internet lenders serving Virginia borrowers.
What are the current title loan laws in Virginia?
Virginia caps title loan principal at $2,500, limits interest to a 36 percent simple annual rate, and requires every lender to hold a license from the Bureau of Financial Institutions. Loan terms generally run between six and 24 months, and total fees are capped as a percentage of the original loan amount under § 6.2-2216.
How do I legally get out of a Virginia title loan?
You can pay off the loan early, since Virginia lenders aren’t permitted to trap you with certain undisclosed penalties, and reviewing your contract’s payoff terms is the first step. If a lender charged fees beyond what § 6.2-2216 authorizes or operated without a license, the loan may be void or the fees uncollectible, which is worth raising directly with the Bureau of Financial Institutions through a formal complaint.